How to Buy a House in Ontario, Canada

Insider Tips and Strategies for Successfully Buying Your Dream Home in Canada

Contact Us
Home How to Buy a House in Ontario, Canada
Overview
Ontario Housing Market
First Steps to Homeownership
Location and Budget Planning
Home Buying Checklist
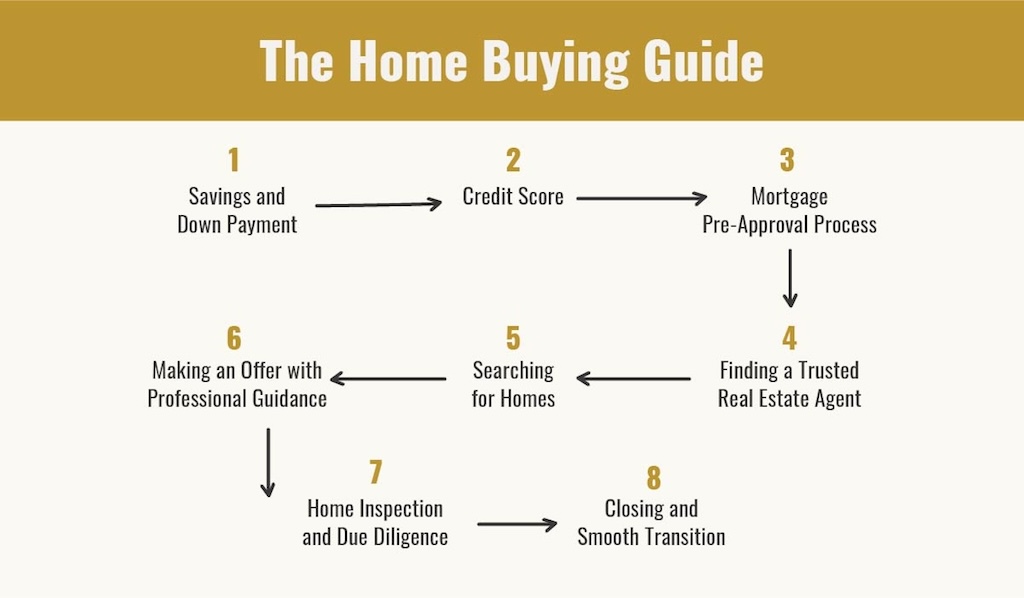
Home Buying Steps
Step 1: Budget
Step 1
Step 2: Down Payment
Step 2
Step 3: Mortgage Pre-Approval
Step 3
Step 4: Find a Real Estate Agent
Step 4
Step 5: Home Search
Step 5
Step 6: Evaluate
Step 6
Step 7: Make an Offer
Step 7
Step 8: Complete
Step 8
Step 9: Closing
Step 9
First-Time Home Buyers in Ontario
Home Buyers in Ontario
Ready to Start Your Ontario Home Search?
Why Choose Us?
Ontario Housing Market

If you are wondering how to buy a house in Ontario, it helps to understand the decisions that come before the property search. Your budget, financing, and closing funds determine which homes you can consider and how confidently you can make an offer.

This 2026 guide covers the steps to buying a house in Ontario, from preparing your finances and choosing a neighbourhood to completing due diligence and receiving the keys. It is designed for first-time buyers, current homeowners planning their next move, and people buying real estate as a long-term investment.

Ontario Housing Market Overview for 2026

GTA buyers have more choice in many market segments than they did during the highly competitive years earlier in the decade. In August 2026, the Toronto Regional Real Estate Board (TRREB) Market Watch reported an average GTA selling price of $993,410, down 2.7% year over year. However, the balance between buyers and sellers still varies by neighbourhood, property type, and price range.

A well-priced freehold home near transit or a sought-after school may attract competition, while some condos give buyers more negotiating room. Mortgage rates, property taxes, condo fees, and expected repairs also affect affordability, so compare the total monthly cost and recent local sales rather than trying to time the entire GTA market.

Location and Budget Planning

Find a GTA Area That Fits Your Priorities

Use the home-buying quiz to compare GTA locations based on the type of community, commute, and amenities that matter to you.

Home Buying Quiz
Which setting do you prefer for your ideal lifestyle?
Start Over
Home Buying Steps

Home Buying Checklist

Buying a home is a big step and can sometimes feel confusing. Whether it’s your first time buying a house or you’ve done it before, it’s important to know what to look out for and how to make good choices. These are home-buying steps we suggest you to follow:  

home buying checklist

Step 1

1. Determine Your Budget

Before browsing listings, review your household income, savings, credit, and existing debts. Then set a comfortable monthly limit that leaves room for emergencies and your other financial goals. A lender’s maximum approval is not automatically the right spending limit for you.

Include the full cost of ownership in your budget:

  • Mortgage principal and interest
  • Property taxes and home insurance
  • Utilities and routine maintenance
  • Condo or POTL fees and possible parking costs
  • Travel or commuting expenses
  • Monthly cost for rental items
  • A reserve for repairs and unexpected expenses

One of the most important steps when buying a house is deciding what you can comfortably carry each month, not simply what you may qualify to borrow.

Step 2

2. Save for Your Down Payment and Closing Costs

Canada’s minimum down payment depends on the purchase price:

  • $500,000 or Less: 5% of the purchase price
  • More Than $500,000 But Less Than $1.5 Million: 5% of the first $500,000 and 10% of the remaining portion
  • $1.5 Million or More: 20% of the purchase price

If your down payment is below 20%, you will generally need mortgage loan insurance. A larger down payment can reduce the amount borrowed and may avoid the insurance premium, but do not use every available dollar. You will also need funds for closing and immediate ownership costs.

Beyond the down payment, budget approximately 1.5% to 4% of the purchase price for closing-related costs. These may include land transfer tax, legal fees, title insurance, adjustments, lender or appraisal fees, and tax on mortgage default insurance. Toronto buyers may fall toward the higher end, although first-time buyer rebates can reduce the total. Keep separate funds for moving and immediate repairs.

Eligible first-time buyers may be able to combine a First Home Savings Account (FHSA) with the Home Buyers’ Plan. The dedicated first-time buyer section below explains the current limits and land transfer tax rebates.

Step 3

3. Get Mortgage Pre-Approved

A mortgage pre-approval gives you a more reliable price range before you start making offers. The lender will typically review your income, employment, credit, down payment, and debts. Depending on your situation, you may need pay stubs, tax documents, bank statements, and proof showing where the down payment came from.

Pre-qualification is generally an early estimate based largely on information you provide. Pre-approval usually involves more verification and may include a rate hold, often for 90 to 120 days depending on the lender. Neither guarantees final approval because the lender must still approve the property and confirm that your finances have not materially changed.

Getting pre-approved can help you set a realistic search range, estimate payments, and identify financing issues before an offer deadline. Before applying, learn more about mortgage pre-approval versus pre-qualification for GTA buyers.

Step 4

4. Find the Right Real Estate Agent

A buyer’s agent can help you find suitable listings, compare recent sales, arrange viewings, and prepare an offer based on the property and current competition. Before signing a representation agreement, ask about the agent’s experience in your target communities and property type, how they communicate, and how their services and compensation work.

home buying deal

Big City Realty helps buyers compare GTA neighbourhoods, evaluate local sales, and understand the practical effects of deposits, conditions, closing dates, and inclusions. The goal is to explain both the strengths and drawbacks of a property before you decide how to proceed.

Step 5

5. Search for the Right Home and Neighbourhood

Define 4 essentials before booking viewings: location, property type, comfortable price range, and must-have features. Separating needs from preferences will make it easier to compare trade-offs involving space, commute, and monthly costs.

When buying a home in Ontario, evaluate the neighbourhood as carefully as the property. GTA buyers should consider:

  • GO Transit, Toronto Transit Commission (TTC), and highway access
  • Actual travel time during weekday traffic
  • Nearby shops, healthcare, and recreation
  • School boundaries and admission requirements
  • Planned construction or development nearby
  • Property taxes, utilities, and condo fees
  • Parking availability and local restrictions
  • Resale appeal for the property type

Visit promising areas at different times. A weekend showing may not reveal weekday congestion, evening noise, or parking demand.

Step 6

6. View and Evaluate Properties

Once you’ve found a home that ticks all your boxes, it’s time to make an offer. 

This step requires careful consideration of the home’s value, your budget, and any competing offers. 

Your real estate agent will be essential here, guiding how much to offer and any conditions to include, such as financing approval or a home inspection.

Step 7

7. Make a Strong, Informed Offer

An Agreement of Purchase and Sale (APS) is a legally binding contract. It normally addresses:

  • Purchase price and deposit
  • Proposed closing date
  • Fixtures and chattels included or excluded
  • Financing, inspection, and other conditions
  • The offer expiry time (often referred to as the the “irrevocability”)

Use recent comparable sales, property condition, days on market, and current competition to shape the offer. Price is only one factor. A suitable closing date, appropriate deposit, and clear terms may also matter to the seller.

Financing and inspection conditions can protect you if approval or property findings create a problem. Removing a condition may make an offer more attractive, but it also increases your risk. Review that trade-off with your agent, lender, and lawyer before signing.

Step 8

8. Complete Your Due Diligence

After acceptance, complete every condition and review by its deadline. Depending on the property, this may involve:

  • Completing the professional home inspection
  • Confirming final mortgage approval and any lender appraisal
  • Reviewing title, easements, liens, and property documents with your lawyer
  • Confirming that suitable home insurance is available
  • Checking permits and warranties for major renovations

For a condo, have an Ontario real estate lawyer review the status certificate and supporting documents. Pay attention to maintenance fees, the reserve fund, insurance, rules, legal proceedings, and known or proposed special assessments. Confirm what the monthly fee covers and whether the building’s finances and maintenance history fit your plans.

For a broader building-level review, explore how to evaluate a condo building before you buy. You can also learn what a status certificate is and why it matters when buying a condo before deciding whether to proceed.

Step 9

9. Close the Deal

Your real estate lawyer manages the legal transfer of ownership, reviews title, prepares closing documents, calculates adjustments, and tells you how much money must be provided. You will also need to finalize the mortgage, arrange insurance, and deliver the closing funds in the form and by the deadline your lawyer specifies.

Closing costs can include the Ontario Land Transfer Tax (LTT), Toronto’s Municipal Land Transfer Tax (MLTT) for a Toronto property, legal fees, title insurance, and adjustments for prepaid property taxes or utilities. Shortly before closing, complete the final walkthrough to confirm the home remains in the agreed condition and the included items are still present. Keys are released after the transaction closes, and ownership is registered.

Home Buyers in Ontario

Eligible first-time buyers may be able to reduce the amount they need to save or pay at closing through:

  • FHSA: Tax-deductible contributions and qualifying tax-free withdrawals, with an annual contribution limit of $8,000 and a lifetime limit of $40,000.
  • HBP: A qualifying withdrawal of up to $60,000 from a registered retirement savings plan (RRSP), followed by repayment according to the program rules.
  • Ontario LTT Refund: A refund of up to $4,000 for an eligible first-time buyer.
  • Toronto MLTT Rebate: An additional rebate of up to $4,475 for an eligible purchase within Toronto.

Each program uses its own eligibility rules. Previous home ownership, a spouse’s ownership history, residency, and how the property will be used may affect qualification. Confirm the amounts available to you before including them in your closing budget.

For a closer look at the programs you may be able to combine, explore our guide to first-time home buyer incentives in Ontario in 2026.

Why Choose Us?

Ready to Start Your Ontario Home Search?

Big City Realty can help you narrow your GTA search, compare properties and recent sales, and prepare an offer that reflects your budget and priorities. If you are ready to buy a house in Ontario, complete the form to speak with a buyer’s agent.

Contact Us

FAQ

Plan for your down payment plus 1.5-4% of the purchase price in closing costs. The minimum down payment is 5% on the first $500,000 and 10% on the portion from $500,001 to $1.5M, plus a 3-6 month emergency buffer. We’ll work out a personalized number with you before you tour your first home.

Pre-qualification is a rough estimate based on what you tell the lender. Pre-approval means the lender has pulled your credit, verified your income, and locked a rate for 90-120 days.

Ontario charges provincial Land Transfer Tax on every purchase, and the City of Toronto adds a municipal LTT on top. Combined, it can run into tens of thousands on a typical GTA purchase. First-time buyers can claim a rebate of up to $4,000 provincially and $4,475 in Toronto.

Federally regulated lenders qualify you at the higher of your contract rate plus 2% or the benchmark rate. So if you’re approved at 5%, you actually need to demonstrate you could carry payments at around 7%. Whether you pass depends on income, debts, and down payment; we run the numbers before you fall for a listing you can’t qualify for.

Yes. Eligible first-time buyers can contribute up to $8,000 per year ($40,000 lifetime) to the FHSA tax-deductibly and also withdraw up to $60,000 from RRSPs under the Home Buyers’ Plan. Used together, that’s serious down-payment power.

For resale homes in the GTA, the typical timeline is 30-90 days from identifying the right property to closing, about 5-15 business days from an accepted offer to firming up conditions, then a closing period the parties agree to. Pre-construction is different and can take years.

Generally no. Under the federal Home Buyers’ Plan and the Ontario LTT rebate, you don’t qualify if your spouse has owned a home that you lived in during the relationship. There are nuanced exceptions; confirm with your accountant and us.

In Ontario, the buyer’s agent’s commission is typically paid from the seller’s proceeds at closing, meaning you usually pay your buyer’s agent nothing directly on a resale purchase. Following recent industry changes, the compensation is disclosed upfront in a written Buyer Representation Agreement, so there are no surprises.