Rent or Buy? Run Your Numbers.
Take the 60-second quiz, then see what renting and buying really cost you over time, with current rates and Ontario rules built in.
The 60-second quiz
Six quick questions. No email needed.
Rent vs. buy calculator
Change any number and the results update instantly. It uses Canadian mortgage math, mortgage insurance, Ontario and Toronto land transfer tax with first-time buyer rebates, and 2026 property tax rates.
Advanced assumptions
Rates as of October 21, 2026: lowest insured 5-year fixed about 4.3% to 4.6%, big-bank average about 5.2%. Property tax uses 2026 municipal rates.
Try a real GTA scenario
Estimates only. See how we set the starting assumptions.
When renting wins
- You may move within 2 to 4 years: buying and selling costs need time to pay back
- You’re still building your down payment, ideally in a First Home Savings Account
- Your income is new, variable or about to change
- You want flexibility and no repair bills
When buying wins
- You’ll stay 5 years or more
- You have at least 5% to 10% down plus closing costs
- Your owning cost is close to the rent you’d pay
- You want a home you control and equity you keep
The 5% rule, done right
A quick rule of thumb: compare rent with the costs of owning that you never get back. Those are mortgage interest, property tax, upkeep and what your down payment could have earned invested. Together they often add up to roughly 5% of the home’s value per year.
Divide that by 12. If a similar home rents for less, renting is usually cheaper; if it rents for more, buying usually is. The part of your mortgage payment that pays down the loan is not a cost; it’s savings.
Programs worth knowing in 2026
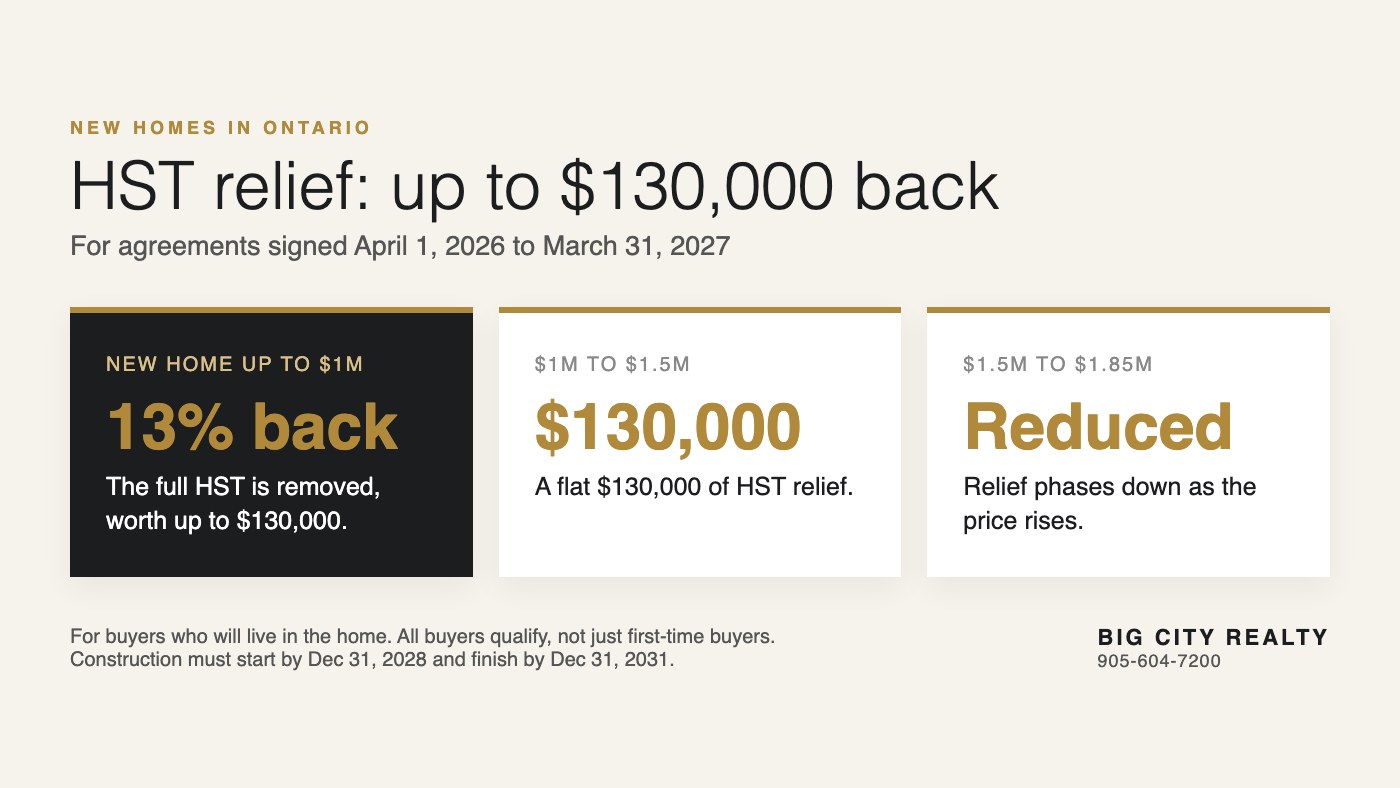
- HST relief on new homes for buyers who’ll live in them: up to $130,000 back on agreements signed by March 31, 2027
- First Home Savings Account: tax-deductible deposits, tax-free withdrawal for your first home
- Home Buyers’ Plan: borrow from your RRSP toward your down payment
- First-time buyers and buyers of new builds can use 30-year amortization on insured mortgages
- First-time buyer land transfer tax rebates: up to $4,000 in Ontario, plus up to $4,475 in Toronto
Get your personal rent vs. buy plan
Tell us your situation. A Big City Realty agent will run your numbers and call you with an honest recommendation, whether that’s renting or buying.
Prefer to talk? Call 905-604-7200 or email sales@bigcityrealty.ca.
Frequently asked questions
When does buying beat renting in the GTA?
Usually after about 5 years, if your owning cost isn’t far above rent for a similar home. Closing costs on the way in and selling costs on the way out need time to pay back. Use the calculator above with your own numbers.
How much do I need for a down payment?
At least 5% of the first $500,000 and 10% of the portion above it, up to $1.5 million. Homes at $1.5 million or more need 20% down. With less than 20%, you also pay mortgage insurance, which is added to your mortgage.
What closing costs should I budget for?
Mostly land transfer tax (Ontario, plus Toronto’s municipal tax inside Toronto), legal fees and title insurance, and in Ontario 8% PST on any mortgage insurance premium. First-time buyers get land transfer tax rebates.
Is rent money wasted?
No. Rent buys a place to live with flexibility and no repair bills. Owners also pay costs they never get back, like interest, property tax and upkeep. The fair comparison is rent against those costs, not against the whole mortgage payment.
Can you help either way?
Yes. We’re the leasing team behind 500+ leases in Leaside’s Upper East Village, and we help buyers across the GTA. We’ll tell you honestly which makes more sense for you.
How we set the starting assumptions (October 2026). These are reasonable long-run defaults, not forecasts. Change any of them under Advanced assumptions. Mortgage rate 4.5%: between the lowest insured 5-year fixed rates (about 4.3% to 4.6%) and the big-bank average (about 5.2%) reported October 19 to 21, 2026. Home values +3% a year: deliberately conservative. TRREB’s average Toronto-area price rose from $70,830 in 1979 to $819,305 in 2019, about 6.3% a year, but prices have fallen since the 2022 peak, so we use a figure close to long-run inflation. Rent +2.5% a year: Ontario’s 2026 rent increase guideline is 2.1% for most existing tenancies; units first occupied after November 15, 2018 are not capped, so we use a slightly higher figure. Investment return 5% a year: an estimate for a balanced, long-term portfolio before fees. It is what the renter is assumed to earn on the money not spent buying. Upkeep 0.5% of value a year (a condo estimate; houses often need 1% or more), selling costs 5% (commission and legal, estimate), property tax at 2026 municipal rates, and land transfer tax and mortgage insurance at current Ontario rules. Not included: HST relief on new homes, because the amount depends on how each builder prices HST into the home. Ask us for the number on a specific home. Scenario prices come from current listings (October 2026); the Pickering town rent is an example. This calculator is an estimate, not financial or tax advice. Your lender, lawyer and accountant confirm the final numbers.